
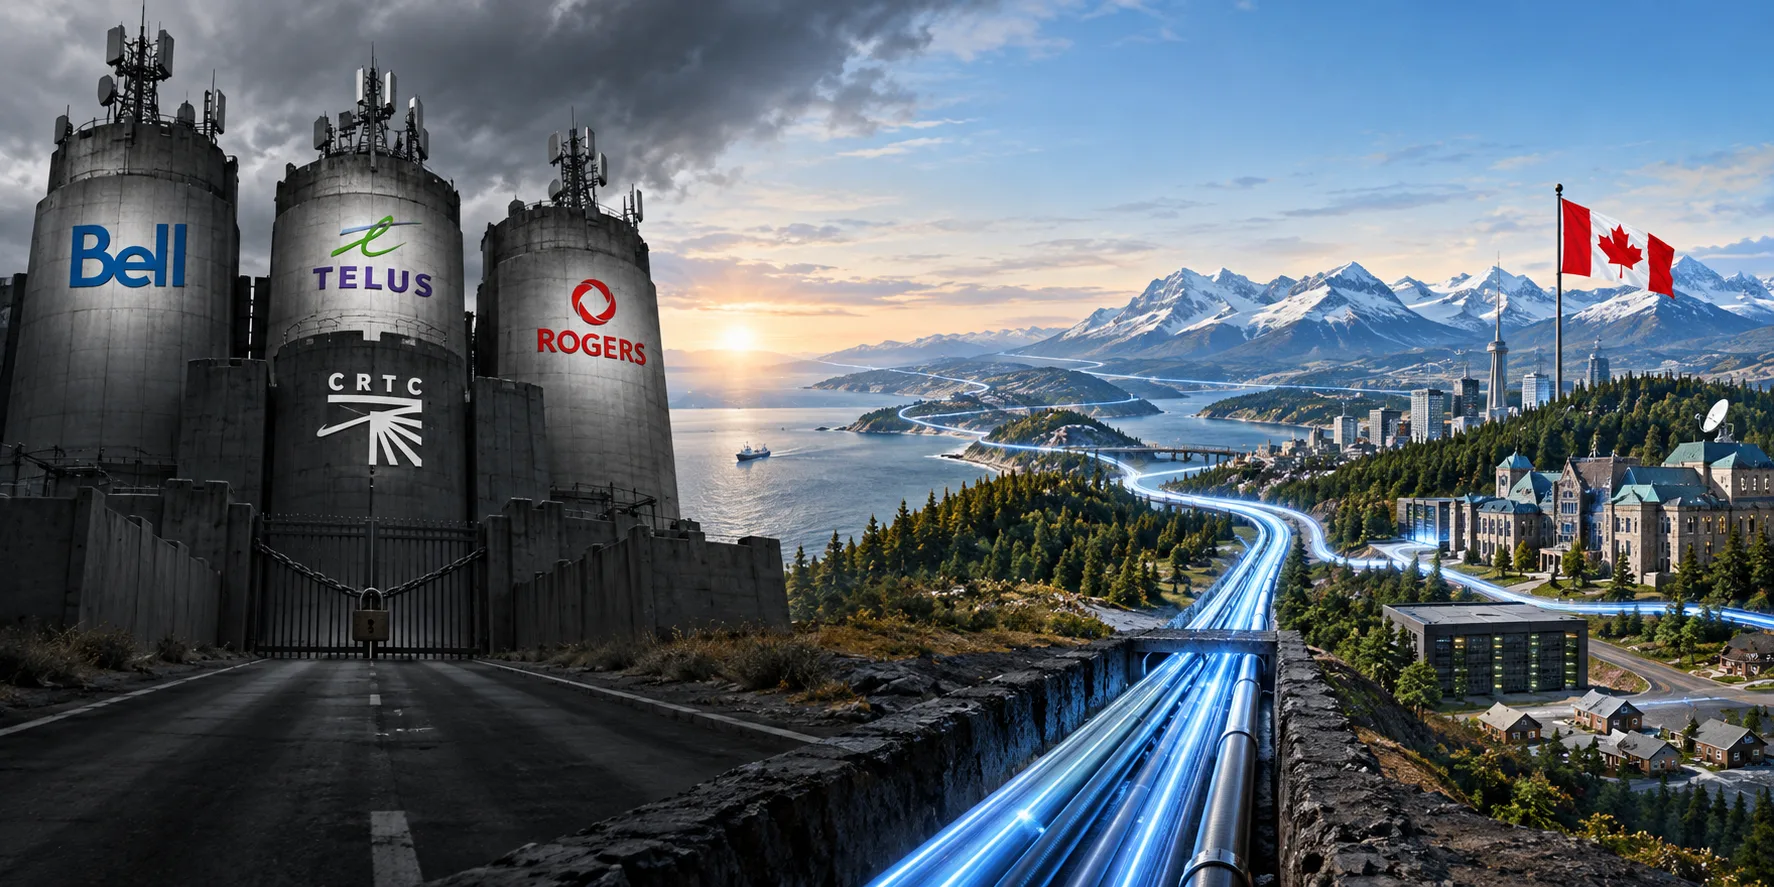
Canada is proposing a sovereign broadband backbone, and the easiest way to build it is also the worst one: hand the money to Bell, Rogers and TELUS, who already hold roughly 90% of wireless revenue and subscribers. Australia, New Zealand and Singapore all solved this by separating the infrastructure from the services running on it. NBN Co is wholesale-only and cannot compete with its own customers. Chorus is barred from selling to end users. Singapore split passive fibre and ducts from active network operations. Canada did the opposite, built vertically integrated networks first, then spent years at the CRTC trying to regulate competition back in. Build the digital Trans-Canada Highway once, keep it Canadian, require equivalent access, and let everyone compete over what runs on it.
Canada is proposing a sovereign broadband backbone connecting the country coast to coast to coast, with more direct and secure connections to Europe and Asia. It could be transformational.
But please. Don’t spend public money building infrastructure that ultimately becomes another competitive advantage for Bell, Rogers and TELUS.
Instead, Canada should build a neutral national fibre layer that every qualified Canadian carrier, ISP, cloud company, data centre, university and government agency can access on equivalent terms. Think of it as a digital Trans-Canada Highway. Government builds or owns the road. Companies compete over what they do on it.
And we don’t have to invent the model.
Australia already did it
Australia created NBN Co to build its National Broadband Network. NBN Co remains wholly owned by the Australian government, but here’s the important part: it’s a wholesale network. It doesn’t compete with the internet providers using its infrastructure to reach customers. Australian law requires NBN Co to provide access on an open, transparent and non-discriminatory basis, with competition oversight from the Australian Competition and Consumer Commission.
The company that owns the highway isn’t also operating the biggest trucking company on it while setting the tolls its competitors have to pay. Australia deliberately separated those roles.
New Zealand did something similar
New Zealand took a different route with its Ultra-Fast Broadband program. The government invested alongside private partners to create open-access, wholesale-only fibre infrastructure, built around principles of equivalence and interoperability.
New Zealand also split its incumbent Telecom New Zealand into Spark, which sells telecommunications services, and Chorus, which operates much of the underlying network infrastructure. Chorus is restricted from selling telecommunications services directly to end users.
Again, the principle is simple: own the infrastructure, let other companies compete over services.
Singapore separated the layers
Singapore went further. Its nationwide broadband strategy deliberately separated passive infrastructure such as fibre and ducts from active network operations and retail telecommunications services. Infrastructure operators must give qualifying service providers access under regulated interconnection arrangements.
Australia, New Zealand and Singapore chose different structures, but all recognized the same problem: the company controlling essential infrastructure shouldn’t be able to use that infrastructure to disadvantage companies competing against it.
Canada should pay attention.
Canada’s approach hasn’t worked particularly well
Canada has largely done the opposite. Bell, Rogers and TELUS remain extraordinarily powerful because they don’t just sell telecommunications services, they control enormous amounts of the infrastructure required to deliver them.
According to the Competition Bureau, Bell, Rogers and TELUS accounted for 89.5% of wireless revenue and 86.9% of wireless subscribers in 2023. Incumbent telephone and cable companies also captured 87.3% of home internet revenue and 88.2% of subscribers. The Competition Bureau describes Canada’s telecommunications markets as highly concentrated.
Canadians don’t need statistics to know what that can feel like. Anyone who has spent an afternoon waiting for a technician, arguing about a bill, negotiating a renewal discount, sitting through an outage or trying to figure out why their internet package suddenly costs more has felt the customer-service side of limited competition.
But the deeper problem is structural. Smaller competitors often need access to infrastructure controlled by the same giant companies they’re trying to compete against. The CRTC has spent years trying to regulate around that contradiction.
The CRTC has been playing catch-up
Canada tried to create competition through increasingly complicated wholesale-access regulations rather than designing competition into the infrastructure itself. The results haven’t been encouraging.
The CRTC previously pursued a disaggregated wholesale fibre-access model, then concluded it wasn’t viable for supporting broad competition. Between 2020 and 2022, subscriptions using the large telephone companies’ wholesale high-speed networks fell by more than 40%. Overall wholesale subscriptions dropped 15%, while Canada’s retail internet market grew about 5%.
Eventually the CRTC changed direction and required large telephone companies to provide competitors workable aggregated access to fibre networks. That’s an improvement, but it also shows the problem: Canada built vertically integrated infrastructure first and then spent years trying to regulate competition into it afterward. Australia, New Zealand and Singapore designed competition much closer to the infrastructure layer. We have a chance not to repeat that mistake.
Build a Canadian digital highway
Imagine the sovereign broadband network as national infrastructure rather than another telecom network. A Canadian national fibre entity could own strategic long-haul fibre, ducts, points of presence and potentially international cable landing infrastructure. It wouldn’t sell internet packages. It wouldn’t bundle television. It wouldn’t compete with the companies using it. Its product would be infrastructure.
Bell could buy capacity. Rogers could buy capacity. TELUS could buy capacity. So could TekSavvy, Beanfield, a Canadian cloud company, an AI data centre in Saskatchewan, an Indigenous-owned ISP, a university or the Government of Canada. Same infrastructure. Transparent rules. Equivalent access.
That could change the economics of entering the Canadian telecommunications and digital-infrastructure markets. A regional ISP wouldn’t need to recreate a national fibre network. A Canadian cloud company could connect data centres across the country without depending exclusively on one of Canada’s dominant telecommunications companies. AI data centres could locate near abundant Canadian electricity rather than only where an incumbent carrier happens to offer economical connectivity. And governments could build geographically redundant Canadian routes for critical services.
Sovereignty should mean more than Canadian fibre
This matters even more because broadband is becoming part of a much larger Canadian digital-sovereignty strategy. Canada is talking about sovereign AI compute, Canadian data centres, Canadian energy and infrastructure operating under Canadian law. Connectivity is the layer connecting all of it.
But replacing dependence on foreign infrastructure with dependence on three enormous Canadian telecommunications companies isn’t necessarily digital sovereignty. A truly sovereign network should be Canadian-controlled, geographically diverse, resilient and available to many Canadian operators. That could eventually include Canadian-controlled Atlantic routes to Europe, Pacific routes to Asia and northern infrastructure connecting the Arctic.
Private companies could compete hard over services running across those networks. They just wouldn’t own the public highway.
We have a rare opportunity
Canada doesn’t often get to redesign fundamental infrastructure from scratch. This is one of those moments.
The easiest approach would be familiar: hand billions in incentives and financing to Canada’s incumbent telecommunications companies and ask them to build more fibre. Twenty years from now, we could have another CRTC proceeding trying to figure out what competitors should pay to access infrastructure taxpayers helped finance.
Or we could learn from Australia, New Zealand and Singapore. Build the fibre once. Keep strategic infrastructure Canadian. Require open, equivalent access. Separate ownership of the highway from competition on the highway. Then let Bell, Rogers, TELUS, and hundreds of companies that don’t exist yet, compete over what they can build on top of it.
That’s a much more interesting definition of a sovereign Canadian broadband network.
Frequently Asked Questions
What is an open-access wholesale broadband network?
It’s infrastructure that sells capacity to service providers instead of selling internet packages to households. The entity owning the fibre, ducts and points of presence doesn’t compete with the companies buying access from it. Think of it as a digital Trans-Canada Highway: government builds or owns the road, and companies compete over what they do on it.
How does Australia’s NBN Co work?
NBN Co is wholly owned by the Australian government and operates as a wholesale network only. It doesn’t compete with the internet providers using its infrastructure to reach customers. Australian law requires access on an open, transparent and non-discriminatory basis, with competition oversight from the Australian Competition and Consumer Commission. The company that owns the highway isn’t also running the biggest trucking company on it while setting the tolls.
What did New Zealand and Singapore do differently?
New Zealand’s Ultra-Fast Broadband program invested alongside private partners to build open-access, wholesale-only fibre, and split incumbent Telecom New Zealand into Spark for services and Chorus for network infrastructure, with Chorus barred from selling directly to end users. Singapore separated passive infrastructure such as fibre and ducts from active network operations and retail services, requiring infrastructure operators to give qualifying providers access under regulated interconnection. Three different structures, one shared principle.
How concentrated is Canada’s telecom market?
The Competition Bureau found Bell, Rogers and TELUS accounted for 89.5% of wireless revenue and 86.9% of wireless subscribers in 2023. Incumbent telephone and cable companies captured 87.3% of home internet revenue and 88.2% of subscribers. The Bureau describes these markets as highly concentrated.
Why hasn’t CRTC wholesale regulation fixed this?
Because Canada tried to regulate competition into vertically integrated infrastructure after the fact rather than designing it in. The CRTC pursued a disaggregated wholesale fibre-access model and later concluded it wasn’t viable for broad competition. Between 2020 and 2022, subscriptions on the large telephone companies’ wholesale high-speed networks fell by more than 40% and overall wholesale subscriptions dropped 15%, while the retail internet market grew about 5%. The CRTC eventually required workable aggregated fibre access, which helps, but the sequencing is the problem.
Wouldn’t the incumbents still use the network?
Yes, and that’s the point. Bell, Rogers and TELUS could all buy capacity on equivalent terms, alongside TekSavvy, Beanfield, Canadian cloud companies, an AI data centre in Saskatchewan, an Indigenous-owned ISP, universities and the Government of Canada. Nobody is excluded. What changes is that no competitor also controls the tolls.
Isn’t a Canadian-owned network already sovereign?
Not necessarily. Replacing dependence on foreign infrastructure with dependence on three enormous Canadian telecommunications companies isn’t really digital sovereignty. A sovereign network should be Canadian-controlled, geographically diverse, resilient and available to many Canadian operators, potentially including Canadian-controlled Atlantic routes to Europe, Pacific routes to Asia and northern infrastructure connecting the Arctic.
What would this change for new entrants?
It changes the economics of entry. A regional ISP wouldn’t need to recreate a national fibre network. A Canadian cloud company could connect data centres across the country without depending exclusively on one dominant carrier. AI data centres could locate near abundant Canadian electricity instead of only where an incumbent happens to offer economical connectivity. Governments could build geographically redundant Canadian routes for critical services.
